
Across 199 trading days, the three US dogecoin funds recorded zero net flows on 166 of them. Not outflows. Nothing at all. The generic listing standards made these products easy to launch, and the first casualty shows what launching easily actually reveals.
Summary
- Bitwise told the SEC on September 10 it will liquidate the Bitwise Dogecoin ETF, with final trading expected on October 14 and cash distribution around October 22.
- The fund held roughly $722,000 in net assets as of September 8, backed by about 8.2 million DOGE.
- Across 199 trading days for all three US dogecoin funds, net flows were positive on 28 days, negative on five, and zero on 166 days.
- Dogecoin ETFs generated roughly $300 million in cumulative trading volume, compared with $1.5 billion for Zcash products and $2.1 billion for Hyperliquid-linked products.
- Bitwise cited optimising its product range as the reason for the closure, while its Hyperliquid fund continued attracting buyers.
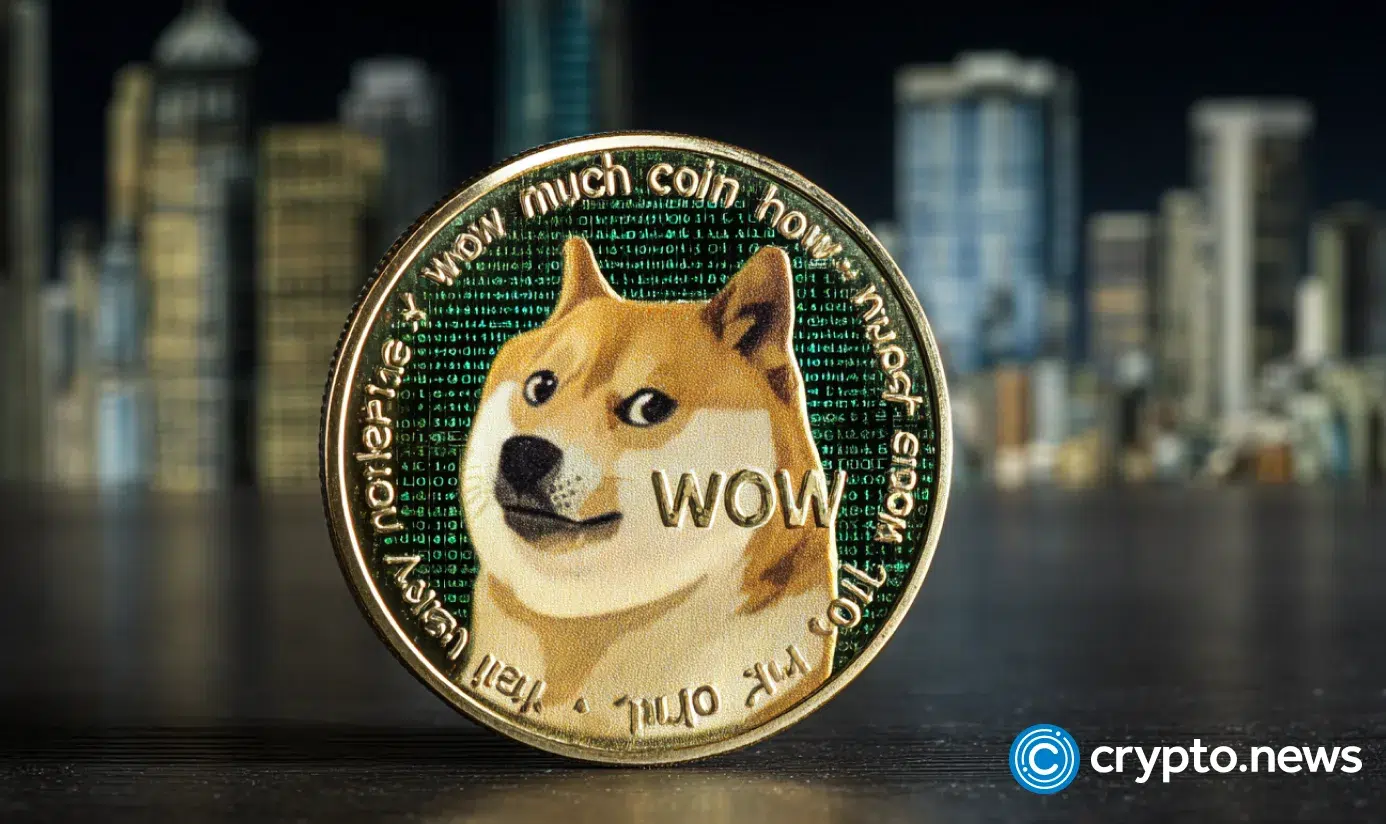
The interesting number in the dogecoin ETF story is not the $722,000 the fund held when Bitwise decided to close it. It is 166. That is how many trading days, out of 199 covering all three US dogecoin funds, recorded combined net flows of exactly zero. Not money leaving. Not money arriving. Nothing happening at all, on more than four days in five, for the better part of a year, in a regulated product tracking one of the most recognised assets in cryptocurrency. Dogecoin has a brand most equities would pay a fortune for. It has been mentioned on national television, promoted by the wealthiest man alive, and carried a $13 billion market capitalisation while its dedicated ETF could not hold a million dollars. Bitwise filed to liquidate on September 10. The fund had a 0.34% expense ratio, among the lowest in its category, and traded on the New York Stock Exchange’s Arca platform with the same access any investor has to any other listed fund. Everything the industry spent years arguing for, it had. What it did not have was anyone who wanted it.
What Bitwise filed
The mechanics first, because shareholders need them and most coverage buried them.
Bitwise Investment Advisers announced on September 10 that it would liquidate and close the Bitwise Dogecoin ETF, effective that date, and filed a Form 8-K with the SEC. The last day of trading on NYSE Arca is expected to be October 14. Shareholders may sell in the secondary market until the close of trading that day.
After that, the fund ceases operations. On October 22, remaining shareholders receive the net asset value of their shares as of October 21, distributed in cash. No action is required from holders.
Two practical points for anyone holding it. Selling on the exchange before October 14 gets whatever a buyer is paying at that moment, and in a thinly traded fund that price can deviate from net asset value in either direction by more than it would in a liquid product. Holding to the end means carrying full dogecoin price exposure until October 21, then receiving cash, which may have tax consequences depending on the holder’s basis.
The stated reason was that Bitwise is optimising its product range to meet evolving investor needs. The firm did not cite volume, performance, or demand.
The 166 days
Here is the number that makes this a story instead of a footnote.
Analysis covering 199 trading days across the three US dogecoin funds found positive net inflows on 28 days and net outflows on five. On the remaining 166 days, more than 83% of the sample, combined net flows were zero.
Sit with what zero means in this context. It does not mean the funds performed badly. It means that on four days out of five, across every dogecoin ETF available to American investors, not one dollar was created and not one dollar was redeemed. The product existed, was quoted, was accessible through any brokerage account, and was untouched.
For comparison, a fund with outflows at least has holders making decisions. Persistent zero-flow days describe a product that nobody is arriving at and nobody is leaving, because almost nobody is there.
BWOW’s own trajectory fits. Roughly $3 million of first-day trading volume in late November 2025, suggesting real initial curiosity, then nothing sustained. Net assets of $721,815 as of September 8, backed by approximately 8.2 million DOGE. Net asset value down about 45% from inception through the end of August, which is a price problem, not a flow problem, but the two compound: a falling asset with no inflows shrinks twice.
The comparison that explains it
Set dogecoin’s funds against what else launched in the same window and the picture sharpens considerably.
Cumulative trading volume in dogecoin ETFs runs to roughly $300 million. Zcash products have done about $1.5 billion. Hyperliquid-linked products about $2.1 billion. And XRP and Solana funds together pulled in around $3 billion, with one analysis noting that dogecoin ETFs took ten months to attract what XRP managed in a single day.
Those numbers describe a selection process, not a general absence of appetite. Institutional and brokerage money is going into altcoin ETFs. It is going into specific ones.
The pattern separating them is not obvious from brand recognition, which dogecoin has in abundance. It tracks something closer to whether an asset has an argument attached. Zcash has a privacy thesis and a protocol upgrade cycle. Hyperliquid has revenue, a buyback, and a market position. XRP has a legal settlement, institutional payment rails, and a pending regulatory determination. Solana has an ecosystem generating fees.
Dogecoin has a following. That is valuable and it is not the same thing as a reason for an allocator to put it in a portfolio, because a following is a reason to buy the token and an argument is a reason to buy the fund.
Grayscale’s competing product illustrates the same point from the other side. GDOG launched days before BWOW and holds roughly $8.7 million, about twelve times what Bitwise managed. That is a substantial relative win and an absolute figure that would embarrass a traditional ETF. Both funds occupied the same awkward middle: too small to be meaningful, too visible to disappear quietly. One is closing.
What the generic listing standards actually did
This is the structural half, and it is the reason the closure matters beyond one ticker.
In September 2025 the SEC approved generic listing standards for commodity-based trust shares on the major exchanges, replacing per-product rule-change filings for qualifying funds and cutting potential approval timelines from as long as 240 days to as little as roughly 75. A commodity qualifies if it trades on a market belonging to the Intermarket Surveillance Group, has underpinned a futures contract on a designated contract market for at least six months, or is tied to an ETF providing at least 40% exposure. Anything failing all three still requires a separate filing.
The effect was a wave. Bitwise itself has projected more than a hundred new US crypto ETFs as timelines compress, and the sector has been launching accordingly.
The industry framed the standards as removing an unfair barrier, and that framing was correct. Approval was a real constraint, it was arbitrary in places, and removing it was an improvement.
What the standards could not do is create demand, and BWOW is the first clean test of the difference. A product that cleared every regulatory hurdle, listed on a major exchange, priced competitively, tracking a top-twenty asset, drew $722,000 and closed inside a year.
The lesson is not that the standards were a mistake. It is that they solved the problem the industry could see and left the one it could not. When approval was hard, every failure could be attributed to access. Now that approval is easy, failures have to be attributed to something else, and the something else is that a regulated wrapper does not make an asset more attractive to someone who did not want the asset.
What this does to the pipeline
If a hundred crypto ETFs are coming, the dogecoin outcome is the base case for a meaningful share of them, and the consequences are worth naming.
Issuers will concentrate. Running an ETF has fixed costs regardless of size: custody, audit, listing fees, compliance, marketing. A fund holding $722,000 at a 0.34% expense ratio generates roughly $2,500 a year in fees, which does not pay for a single line item. Issuers will increasingly launch where they believe assets will follow, which means fewer speculative listings and more products tied to assets with institutional narratives already in place.
Closures will become routine and should be read carefully. A liquidation is not a verdict on the underlying asset. Dogecoin is unaffected by BWOW closing; the token trades, the network runs, holders hold. What closed was one route to exposure, and the closure says something about allocator appetite for that route, not about the asset’s prospects.
And the survivorship math will flatter the category. Funds that fail get liquidated and disappear from the averages. A year from now, aggregate altcoin ETF statistics will look healthier than the launch cohort actually performed, because the cohort’s failures will have been removed from it. Anyone assessing whether altcoin ETFs work should count launches against survivors, not measure the survivors.
The question the category has not answered
Underneath all of this sits an unresolved question about what a single-asset altcoin ETF is for, and dogecoin makes it unusually sharp.
The case for a spot bitcoin ETF was straightforward: institutions with mandates preventing direct custody of digital assets could get exposure through a familiar wrapper, and the amounts involved were large enough that the wrapper’s cost was trivial against the access it provided. That argument worked, and the flows proved it.
Extending it to smaller assets requires the same conditions, and they thin out fast. An allocator who wants dogecoin exposure can buy dogecoin on any major exchange, in any size a retail or small institutional position would require, without a management fee. The wrapper’s value proposition rests on the narrow set of buyers who both want the asset and cannot hold it directly, and for assets outside the largest few, that set is small.
Which suggests the products that work will be the ones where the wrapper adds something beyond access: staking yield passed through, index exposure across multiple assets, or an asset that is actually difficult for institutions to custody. A single-asset fund tracking a liquid token available everywhere is competing with the token itself, and losing on fees.
Bitwise’s own Hyperliquid fund continuing to attract buyers while its dogecoin fund closed is the cleanest evidence available that the issuer understands this. Same firm, same distribution, same regulatory environment, opposite outcomes.
What $722,000 actually buys you
Run the economics of the fund itself and the closure stops looking like a decision and starts looking like arithmetic.
BWOW charged 0.34%, among the lowest expense ratios of any US spot dogecoin product. At $722,000 in net assets, that fee generates approximately $2,455 a year.
Now the costs. A listed ETF requires a custodian, an administrator, a transfer agent, an auditor, legal counsel, listing fees to the exchange, ongoing SEC reporting, market-maker arrangements, and a compliance function. Any one of those is a multiple of $2,455. The fund was not marginally unprofitable. It was generating revenue that would not cover a single invoice.
Which reframes the closure entirely. Bitwise did not shut BWOW because dogecoin disappointed. It shut it because a fund that small cannot pay for its own existence, and the gap was not close enough to wait out. The decision would have been identical at $2 million, and probably at $5 million.
That sets a rough threshold worth carrying into every future launch. A single-asset crypto ETF needs assets somewhere in the tens of millions before the management fee covers operating costs, and needs considerably more before it justifies the issuer’s attention. Grayscale’s competing product at $8.7 million is closer to viable and is not obviously there either.
So the hundred-plus funds Bitwise projects are not a hundred businesses. They are a hundred bets, most of which will resolve the way this one did, and the issuers running them know that better than anyone. Launching cheaply is precisely what makes it rational to launch things that will probably fail.
The brand problem, stated honestly
There is a reading of this that is unfair to dogecoin and worth heading off, because the closure has been used to argue something the data does not support.
Dogecoin did not fail as an asset. It trades around $0.084 with a market capitalisation near $13 billion, which places it among the most valuable cryptocurrencies in existence and ahead of the overwhelming majority of tokens ever created. Its community is durable in a way most projects would envy, its network functions, and its recognition outside crypto exceeds almost every asset in the sector including several with far larger market capitalisations.
What it lacks is the specific thing an ETF buyer is purchasing. An allocator putting client money into a single-asset fund needs a sentence they can write in an investment memo, and that sentence has to be something other than the asset is popular. Zcash buyers can write about privacy demand and a protocol upgrade. Hyperliquid buyers can write about exchange revenue and a buyback. XRP buyers can write about payment rails and regulatory resolution.
There is no equivalent sentence for dogecoin that survives a compliance review, and that is not a criticism of the asset. It is a description of a mismatch between what dogecoin is and what the regulated wrapper is designed to distribute. The token’s appeal was always cultural and participatory, and those qualities do not transmit through a brokerage account.
The honest framing, then, is that dogecoin holders buy dogecoin, and they were never going to buy a fund that charges them to do it less directly. The fund’s failure is evidence about the fund, and the asset’s continued size is evidence about the asset. Both are true and the coverage has mostly picked one.
What the first-day volume was actually measuring
One number in the fund’s history deserves a second look, because it is the kind of figure that gets cited as evidence of demand and measures something else entirely.
BWOW recorded roughly $3 million of trading volume on its first day. That was read at the time as encouraging, and several accounts of the closure still cite it as proof that initial interest existed and then evaporated.
Volume and flows are different things, and on a launch day the difference matters enormously. Trading volume counts shares changing hands, including market makers positioning, arbitrageurs testing the spread against the underlying, and speculative traders taking a short-term view on a newly listed ticker. Net flows count creations and redemptions, which is money actually entering or leaving the fund.
A product can generate meaningful first-day volume with almost no net creation, because the same shares trade repeatedly between professional participants. That appears to be roughly what happened. The fund never built assets, and the flow data across the whole category shows why: on 83% of subsequent trading days, creations and redemptions netted to nothing at all.
This is a general reading error worth carrying beyond this fund. A newly listed ETF’s opening-day volume tells you that market infrastructure functioned and that professionals showed up to make prices. It does not tell you that investors bought. The number that does is net creations, and it is published daily by every issuer.
Applied to the coming wave of launches, the implication is direct. Expect first-day volume figures in every launch announcement, because they are available and they flatter. Check net assets at thirty days instead, which is when the professionals have finished positioning and whatever real demand exists is all that remains.
The two-sided risk in an October wind-down
For anyone holding BWOW right now, the wind-down creates a specific decision with no obviously correct answer, and it is worth setting out because liquidations are unfamiliar to most crypto investors.
Selling before October 14 means accepting the market price a buyer is willing to pay at that moment. In a fund holding under a million dollars with minimal trading, that price can sit meaningfully away from net asset value in either direction. Thin products have wide spreads, and a known liquidation date gives any remaining buyer leverage. Sellers into a wind-down are negotiating from a weak position and the market knows the deadline.
Holding to the end means receiving net asset value as of October 21, which removes the spread risk entirely and replaces it with something else: full dogecoin price exposure for another five weeks, with no ability to exit at a price of your choosing after October 14. If DOGE falls between now and then, the cash received falls with it.
And both paths carry the same tax event. A liquidating distribution is a disposal. Holders sitting on losses may find that useful; holders with gains do not get to defer them by declining to act.
There is no version of this where the holder controls both variables. Selling controls the timing and surrenders the price. Holding controls the price mechanism and surrenders the timing. The right answer depends entirely on the holder’s view of dogecoin over five weeks, which is exactly the question an ETF holder was presumably trying to avoid having to answer precisely.
The wider point, and the one worth carrying into the next closure, is that liquidation risk is a real feature of small funds and it does not appear in any expense ratio. A 0.34% fee looks cheap until the fund closes and forces a disposal at a moment the holder did not choose. Size is a risk characteristic, and in this category it is an underpriced one.
What to watch
The next liquidation. BWOW is unlikely to be the only one. Watch which asset is next and whether it shares dogecoin’s profile of strong retail recognition and weak institutional thesis.
Whether GDOG survives. Grayscale’s dogecoin fund holds roughly twelve times BWOW’s assets and is still small by any conventional measure. Its trajectory over the next two quarters is the second data point on whether dogecoin can sustain regulated exposure at all.
Launch counts against survivor counts. The honest measure of whether the generic listing standards worked. Bitwise has projected over a hundred new funds; the useful number a year from now is how many are still open.
Whether staking products behave differently. Funds passing through staking yield have something a spot token position does not, and the first US spot staked products are now listing. If those hold assets where plain spot funds did not, the wrapper’s value proposition becomes clearer.
Flow concentration. If the next cohort of launches shows the same pattern, with three or four assets taking nearly all the flows, the category will have settled into a shape closer to traditional ETFs than the launch wave implied.
Frequently Asked Questions
What is happening to the Bitwise Dogecoin ETF?
Bitwise announced on September 10, 2026 that it will liquidate and close the fund, ticker BWOW, and filed a Form 8-K with the SEC. The last day of trading on NYSE Arca is expected to be October 14. Remaining shareholders receive the net asset value of their shares as of October 21 in cash on or around October 22, with no action required from them.
How much money was in the fund?
Roughly $722,000 in net assets as of September 8, 2026, backed by approximately 8.2 million DOGE. It launched in late November 2025 with around $3 million of first-day trading volume, which never developed into sustained participation. Net asset value fell about 45% from inception through the end of August.
Why did Bitwise close it?
The firm said only that it is optimising its product range to meet evolving investor needs, and did not cite volume, performance, or demand. The underlying figures are unambiguous: across 199 trading days covering all three US dogecoin funds, net flows were positive on 28 days, negative on five, and exactly zero on 166 days, more than 83% of the sample.
Does this mean dogecoin is in trouble?
No. The token trades, the network operates, and holders are unaffected. What closed is one regulated route to exposure. The closure says something about allocator appetite for that route rather than about dogecoin’s prospects, though it does expose a gap between the asset’s retail recognition and institutional demand for a fund tracking it.
How do dogecoin ETFs compare to other altcoin funds?
Poorly. Cumulative trading volume in dogecoin ETFs runs to roughly $300 million, against about $1.5 billion for Zcash products and $2.1 billion for Hyperliquid-linked ones. XRP and Solana funds together attracted around $3 billion, and one analysis noted that dogecoin ETFs took ten months to gather what XRP managed in a day.
What are the generic listing standards?
Rules the SEC approved in September 2025 allowing qualifying commodity-based trust shares to list without a separate rule-change filing, cutting potential approval timelines from as long as 240 days to roughly 75. A commodity qualifies through one of three routes involving surveillance-group membership, six months of futures history, or existing ETF exposure of at least 40%.
Do the standards explain this closure?
They explain why the fund existed, not why it failed. The standards removed an approval barrier that was real, and removing it was an improvement. What they could not do is generate demand, and BWOW is a clean test of the difference: a product that cleared every hurdle, listed on a major exchange at a competitive fee, and drew under a million dollars.
What should investors take from it?
That regulated access and investor appetite are separate things, and that a single-asset fund tracking a liquid token available on every exchange competes with the token itself while charging a fee. The products likely to survive are those where the wrapper adds something beyond access, such as staking yield or multi-asset exposure. This is educational analysis, not investment advice.
Disclaimer: This article is for information and educational purposes only and does not constitute financial or investment advice. Fund figures reflect issuer disclosures and third-party analysis available at the time of writing. Nothing here is a recommendation to buy, sell, or hold any security or asset. Always do your own research. Information is accurate as of September 15, 2026.
